SIB Cashback, issued by Sharjah Islamic Bank, pays a genuinely strong 10% cashback on online and digital-wallet spend, capped at AED 300 a month, plus 2% on international retail and 1% domestic. It's Sharia-compliant, free in year one, and the annual fee waives if you clear AED 10,000 in yearly spend.
Two mechanics are worth knowing before you redeem: cashback doesn't offset your minimum payment due, and it expires after 36 months. This review covers the rates, the redemption fine print, and what we found — and didn't find — about the real-world experience.
Design & First Impressions
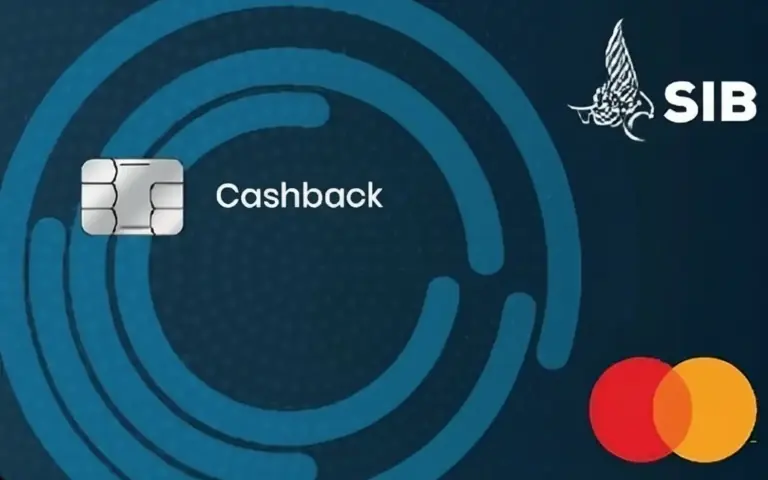
The card uses a dark navy background with a teal concentric-ring motif radiating from the chip, alongside SIB's falcon crest — a more distinctive look than most cashback cards in this segment.

Rewards: How Cashback Adds Up
The headline 10% rate makes SIB Cashback a specialist online-spend card rather than a flat cashback card. It applies to eligible purchases made with saved cards on websites and apps, plus Apple Pay and Samsung Wallet, locally and internationally.
- 10% on online and digital-wallet spend (Samsung Wallet, Apple Pay), capped at AED 300/month
- 2% on international retail, unlimited
- 1% on domestic retail, unlimited
- 0.5% on education, government, utilities, supermarkets, fuel, real estate, quick-service restaurants, insurance, auto dealers, public transport, Salik and charities
- 0.3% on EEA-currency spend
Merchant category and currency rules still matter. Education, government, utilities, supermarkets, fuel and the other listed specific merchants earn 0.5% even when paid online or through a wallet, while transactions settled in EEA currencies earn 0.3%.
AED 3,000 of fully eligible online or digital-wallet spend reaches the AED 300 monthly cap. Beyond that point, the 10% bucket adds no further cashback for that calendar month, so the card works best when the online portion of your budget stays near the cap rather than far above it.
Redemption & Usage
Redeem via the SIB Digital app or call center once you reach AED 100. Cashback posts as a statement credit but does not offset your minimum payment due, and unredeemed cashback expires 36 months after it's earned.
A statement credit lowers the card balance, but it is not treated as the month’s required payment. Keep making at least the minimum payment by the due date, and redeem once the balance reaches AED 100 instead of allowing rewards to sit near their 36-month expiry.
Fees & Eligibility
The ownership cost is modest if the card is used regularly. Year one is free, and from year two the AED 199 fee is waived once annual retail spend exceeds AED 10,000—just over AED 834 a month on average.
| Fee Type | Amount |
|---|---|
Annual Fee | AED 199, free year one, waived above AED 10,000/year spend |
Minimum Salary | AED 5,000 with salary transfer to SIB, AED 8,000 without |
Monthly Profit Rate | 3.49% (41.88% APR, Sharia-compliant Murabaha/Wakala structure) |
Cash Withdrawal Fee | 3.5% or AED 103.95, whichever is higher |
| Fee Type | Amount |
|---|---|
Annual Fee | AED 199, free year one, waived above AED 10,000/year spend |
Minimum Salary | AED 5,000 with salary transfer to SIB, AED 8,000 without |
Monthly Profit Rate | 3.49% (41.88% APR, Sharia-compliant Murabaha/Wakala structure) |
Cash Withdrawal Fee | 3.5% or AED 103.95, whichever is higher |
The lower AED 5,000 salary threshold applies only when salary is transferred to SIB; otherwise the stated minimum is AED 8,000. As with any cashback card, the economics assume the statement balance is paid in full: the 3.49% monthly profit rate can outweigh rewards quickly.
Airport Lounge Access: Two Separate Benefits
The card includes free unlimited access to 10+ lounges across the UAE, KSA, Jordan, Kuwait and Egypt via Mastercard Travel Pass. Separately, a Flight Delay Pass gives access to 1,300+ lounges in 135+ countries if a flight is delayed 1 hour or more, provided you register at least 24 hours in advance. The two are genuinely distinct benefits, not the same perk described twice.
These benefits cover different situations. The regular Mastercard Travel Pass allowance is a small regional lounge network, while Flight Delay Pass has broader global reach but only activates after a qualifying delay and advance registration. It should not be read as unconditional worldwide lounge access.
Kredit Rating: 3.8/5 · Very good
At an assumed AED 5,000/month of spend:
Rewards return — Excellent. About 3.7% effective, roughly AED 2,227/year, driven by the 10% online rate.
Cost efficiency — Outstanding. Zero fee at this spend level, above the AED 10,000/year waiver threshold. Our methodology includes roughly AED 200/year in FX fees.
Benefit value — Fair. The unconditional lounge access and Flight Delay Pass add roughly AED 736/year.
Reward coverage — Limited. Only online/digital-wallet spend clears our meaningful-earning bar; most other categories sit at 1% or below.
Accessibility — Excellent. AED 5,000 with a salary transfer to SIB, AED 8,000 without — a low bar either way.
Bottom line — Very good. Nets to roughly AED 2,763/year — about 4.6% of assumed annual spend. We're holding the published score a touch below the engine's raw suggestion: we found no card-specific user reports, Reddit or otherwise — SIB has a smaller footprint than the major UAE issuers — but general digital-banking sentiment (app-store ratings, aggregator reviews citing call-center responsiveness) points to a less digitally mature experience than the bigger banks already in this catalogue. That's issuer-level sentiment, not evidence about this specific card.
Final Thoughts: Who Should Get This Card?
- Anyone whose spend is heavily online or digital-wallet
- Salary-transfer customers at SIB, where the minimum salary drops to AED 5,000
- Cardholders who'll redeem cashback within 36 months rather than letting it sit
Our guide to pairing UAE credit cards for extra cashback details how to stack the SIB Cashback card with Tabby for amplified rewards. When you settle your Tabby balance online using the SIB card, eligible Tabby transactions can qualify for the 10% cashback rate, contingent on merchant coding and current issuer terms. Remember that the AED 300 monthly cashback cap remains firmly in place.
Skip this card if your monthly spend concentrates on supermarkets, utilities, fuel, education or government payments, all restricted to the reduced 0.5% rate. Digital-wallet or online spenders exceeding AED 3,000 per month will max out the AED 300 cap and see curtailed value. Anyone regularly charging in EEA currencies earns just 0.3%, making this a poor fit.
Kredit provides informational content only and does not offer financial advice. We do not guarantee accuracy and recommend consulting a licensed financial professional before making decisions.