No Foreign Transaction Fee Cards in the UAE 2026
The cost of spending abroad is set by the card, not the exchange rate you happen to get.
See cardsLast updated: - Sourced from official issuer documents and product pages.
How foreign card charges work
Across the UAE cards that publish a rate, the typical card charges 3.14% once the bank's markup and the card network's cross-currency charge are added together. The gap between the cheapest card and the dearest runs to thousands of dirhams a year, and the UAE Card FX Index prices every card in the catalogue.
Two things make up the number. The bank's own markup is the part issuers advertise. The card network adds a cross-currency charge on top, and most issuers mention it only as "network fees may apply". Both land on the same statement line, so the cards below are ranked on the two combined.
A card only reaches zero by waiving both. FAB Travel does, and costs nothing at any level of foreign spend. ADCB Traveller waives its own markup but passes the network charge through, which is why it lands at 1.15% rather than zero. FAB's Z Card lands in the same place from the other direction: FAB charges no international transaction fee on it, and only the network's charge remains.
Two products price by allowance instead of by rate. Sinder costs nothing on the first AED 40,000 of foreign spend each month — it absorbs the card network's charge as well as waiving its own markup — while Ziina waives only its own on the first AED 20,000, so the network's charge still applies there. Both then charge a published rate on the excess. Sinder absorbs the network charge as well as its own markup inside its allowance, so eligible spend within that ceiling prices at zero. Ziina waives only its own markup, so the network charge can still apply inside its allowance. Above each ceiling, the published excess-spend rate matters. Which is why the comparison shows cost at several levels of monthly spend rather than one headline rate.
One product prices by wallet rather than by card. The Liv debit card's own rate is the dearest on this page, but Liv's Multicurrency Account holds dollars, euros, pounds, Australian and Canadian dollars behind that same card, and a purchase in a currency you already hold converts nothing. It is a separate account you open and fund in advance, those five currencies are the entire list, and a balance that runs short falls back to dirhams at the ordinary fee. That makes it a route to zero rather than a cheap card, which is why it sits last here. Read the Liv Multicurrency Account.
Figures come from each card's published fee table or its bank's schedule of charges. Cards that publish neither are left out rather than filled in with an assumption.
No Foreign Transaction Fee Cards in the UAE 2026 compared
A side-by-side snapshot of annual fees, salary requirements, and standout benefits.
| Card | Annual fee | Min. salary | Foreign transaction fee | Why it stands out |
|---|---|---|---|---|
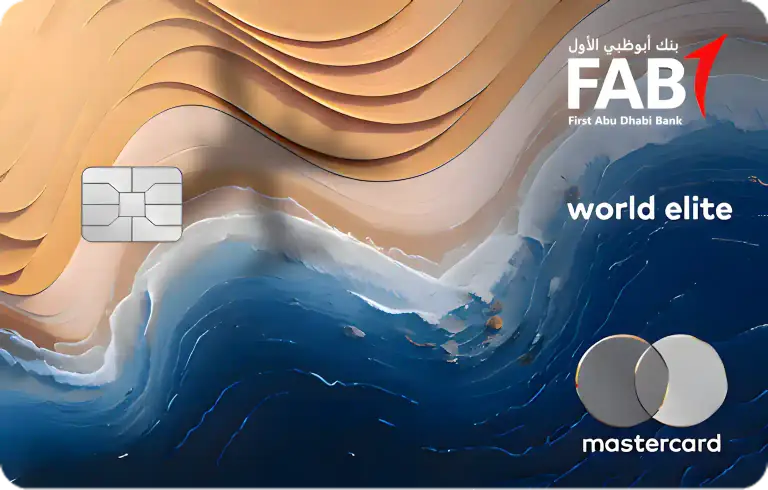 | AED 1,575 | AED 20,000 | None | Waives its own markup and the network charge, so foreign spend costs nothing at any level |
 | Free | N/A | None up to AED 40,000/mo | No Sinder markup on the first AED 40,000 of foreign spend each month, then 0.5% on weekdays and 1.5% at weekends |
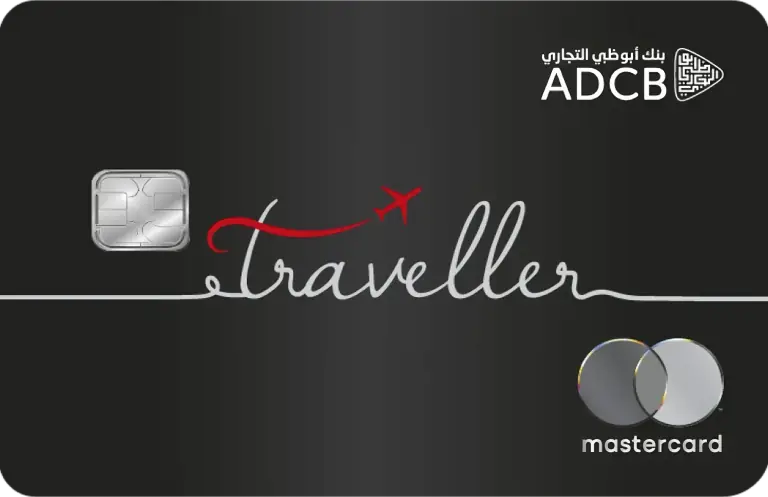 | AED 1,575 | AED 20,000 | 1.15% | No ADCB markup; the card network's cross-currency charge still applies |
 | Free | N/A | 1.15% up to AED 20,000/mo | No markup on the first AED 20,000 of foreign spend each month on the Violet plan |
 | AED 105 | AED 5,000 | 1.15% | No FAB international transaction fee; only the card network's charge applies |
 | AED 7,875 | N/A | 2.14% | 0.99% ADCB markup, the lowest the bank publishes; the card network's charge applies on top |
 | Free | N/A | 4.29% | Reaches zero only through Liv's Multicurrency Account, a separate free account holding five currencies behind the same card |
| Card | Annual fee | Min. salary | Foreign transaction fee | Why it stands out |
|---|---|---|---|---|
| AED 1,575 | AED 20,000 | None | Waives its own markup and the network charge, so foreign spend costs nothing at any level |
| Free | N/A | None up to AED 40,000/mo | No Sinder markup on the first AED 40,000 of foreign spend each month, then 0.5% on weekdays and 1.5% at weekends |
| AED 1,575 | AED 20,000 | 1.15% | No ADCB markup; the card network's cross-currency charge still applies |
| Free | N/A | 1.15% up to AED 20,000/mo | No markup on the first AED 20,000 of foreign spend each month on the Violet plan |
| AED 105 | AED 5,000 | 1.15% | No FAB international transaction fee; only the card network's charge applies |
| AED 7,875 | N/A | 2.14% | 0.99% ADCB markup, the lowest the bank publishes; the card network's charge applies on top |
| Free | N/A | 4.29% | Reaches zero only through Liv's Multicurrency Account, a separate free account holding five currencies behind the same card |
FAB Travel Credit Card
Annual feeAED 1,575
Min. salaryAED 20,000
Foreign transaction feeNone
HighlightWaives its own markup and the network charge, so foreign spend costs nothing at any level
Sinder Founder Card
Annual feeFree
Min. salaryN/A
Foreign transaction feeNone up to AED 40,000/mo
HighlightNo Sinder markup on the first AED 40,000 of foreign spend each month, then 0.5% on weekdays and 1.5% at weekends
ADCB Traveller Credit Card
Annual feeAED 1,575
Min. salaryAED 20,000
Foreign transaction fee1.15%
HighlightNo ADCB markup; the card network's cross-currency charge still applies
Ziina Card
Annual feeFree
Min. salaryN/A
Foreign transaction fee1.15% up to AED 20,000/mo
HighlightNo markup on the first AED 20,000 of foreign spend each month on the Violet plan
FAB Z Credit Card
Annual feeAED 105
Min. salaryAED 5,000
Foreign transaction fee1.15%
HighlightNo FAB international transaction fee; only the card network's charge applies
ADCB Private World Elite Credit Card
Annual feeAED 7,875
Min. salaryN/A
Foreign transaction fee2.14%
Highlight0.99% ADCB markup, the lowest the bank publishes; the card network's charge applies on top
Liv Debit Card
Annual feeFree
Min. salaryN/A
Foreign transaction fee4.29%
HighlightReaches zero only through Liv's Multicurrency Account, a separate free account holding five currencies behind the same card
How to read a foreign transaction fee
1.
The advertised rate is only half of it
Issuers quote their own markup. The card network adds a cross-currency charge on top, usually disclosed as nothing more specific than "network fees may apply". Both hit the same transaction, so compare the two combined.
2.
An allowance is not a rate
A card with a fee-free monthly allowance is the cheapest option in the market below its ceiling and an ordinary one above it. Whether it suits you depends entirely on how much you actually spend abroad in a month.
3.
Dynamic currency conversion undoes all of it
Paying in dirhams abroad hands the conversion to the merchant's provider at its own rate. That charge sits outside the card's fee schedule and can exceed any markup on this page. Always pay in the local currency.
4.
Only stated rates are compared
Every card listed here states its foreign-currency markup. Cards without a stated markup are left out rather than shown with an assumed figure.
How Kredit decides
Methodology and data behind this comparison
Commercial relationships do not determine Kredit Ratings or market rankings. Use the published methods and data sources below to inspect how the comparison is built.
UAE Card FX Index
See the all-in foreign-spend model and every measured card.
Market Position methodology
See how ownership cost and FX feed the broader market benchmark.
Tools & calculators
Put the comparison into your own numbers, or open the underlying market data before you choose.
Data tool
UAE Card FX Index
See the all-in cost of spending abroad across UAE cards at several monthly spend levels.
Calculator
Rewards calculator
Enter your monthly spend and compare the AED value different UAE cards could return.
Calculator
Cash vs miles
Test an award booking against its cash price and see whether using miles is actually good value.
7 cards in the UAE
FIRST ABU DHABI BANK (FAB)
FAB Travel Credit Card
- Salary: AED 20,000+
- Annual Fee: AED 1,575
- Flight voucher after AED 300,000 spend
- 12% cashback on flights and hotel bookings
- No FX fees
SINDER
Sinder Founder Card
- No annual fee
- Digital onboarding
- 0% FX up to AED 40,000/month
- International ATM fee capped at AED 25
- Airport lounge access
ABU DHABI COMMERCIAL BANK (ADCB)
ADCB Traveller Credit Card
- Salary: AED 20,000+
- Annual Fee: AED 1,575
- 10% Cashback on airline tickets
- 10% Cashback on hotel stays
- 1.5% Cashback on all domestic spends
ZIINA
Ziina Card
- Free by default; Violet plan AED 100/month
- No Ziina international transaction fee within each plan's allowance
- Cashback at selected brands (Violet)
- Lifestyle perks bundled with Violet
- No ATM withdrawals
FIRST ABU DHABI BANK (FAB)
FAB Z Credit Card
- Salary: AED 5,000+
- No Annual Fee for the first year
- Free Careem Plus & Noon One for 1 year
- 20% off on monthly subscriptions to Netflix, PlayStation, YouTube, Spotify and more
- No FX fees abroad
ABU DHABI COMMERCIAL BANK (ADCB)
ADCB Private World Elite Credit Card
- ADCB Private clients only
- Exclusive to clients of ADCB Private
- Annual Fee: AED 7,875
- Up to 4 TouchPoints per AED spent
- Low foreign currency transaction fee of 0.99%
LIV DIGITAL BANK BY EMIRATES NBD
Liv Debit Card
- Free with the account
- No annual fee
- Free ENBD ATM withdrawals
- Instant digital issuance
Eligibility criteria
General requirements for credit card applications in the UAE. Exact thresholds vary by bank and card tier.
| Minimum age | 18 on the debit products, 21 on the credit cards |
| Monthly salary | AED 5,000–20,000 |
| Residency | UAE residents with a valid Emirates ID and residence visa |
| Identity | Sinder, Ziina and Liv onboard in-app; the credit cards follow standard bank checks |
| Credit history | AECB is checked for the credit cards; the debit products spend your own balance and open no credit line |
Always confirm the latest eligibility details with the issuing bank before applying.
Documents you will need
Prepare these before you start an application. Some banks accept digital uploads; others require originals at a branch.
UAE nationals
1.Emirates ID
2.Khulasat Al Qaid (Family Book)
3.Salary certificate (less than 30 days old)
4.Bank statements — last 3 months
5.Passport copy
Expats & residents
1.Emirates ID
2.Valid passport with residence visa page
3.Salary certificate or employment letter
4.Bank statements — last 3 months
5.Proof of address (utility bill or tenancy contract)
The final list of required documents may differ based on the bank and card. Self-employed applicants may also need a trade licence and audited financial statements.
Frequently asked questions
Common questions about No Foreign Transaction Fee Cards in the UAE 2026


Not sure which card to pick?
Try the UAE Credit Card Picker
Answer a few quick questions and we'll match the best UAE credit card to your monthly spending — personalised cashback, rewards and perks in under two minutes.